Strong foundations and growth momentum – full year expectations unchanged
Harry Holt, Chief Executive Officer, said:
“Babcock’s strong first-half performance reflects the continued momentum across the Group. We remain focused on growing our established businesses profitably in the UK and internationally, underpinned by multi-year programmes that provide good medium term revenue visibility. Our critical defence, nuclear and associated infrastructure capabilities place us at the heart of allied defence readiness and national strategic resilience requirements. Recognising the critical role we play, especially in the delivery of UK Defence’s highest priority – the Continuous At Sea Deterrent, our commitment to customer delivery remains unwavering.
“As customer requirements evolve, we are increasingly focused on delivering connected, technology-enabled and adaptable solutions that help allied forces maintain operational advantage. Alongside the UK and international growth of our core business, we are actively leveraging our capabilities to capture opportunities in two additional growth vectors: the hybrid nature of warfare and strengthening national strategic resilience.
“We are well positioned to deliver on our medium-term targets and the next phase of growth, with a clear strategy and significant opportunities ahead for long-term shareholder value creation.”
Good progress in first half, full year expectations unchanged
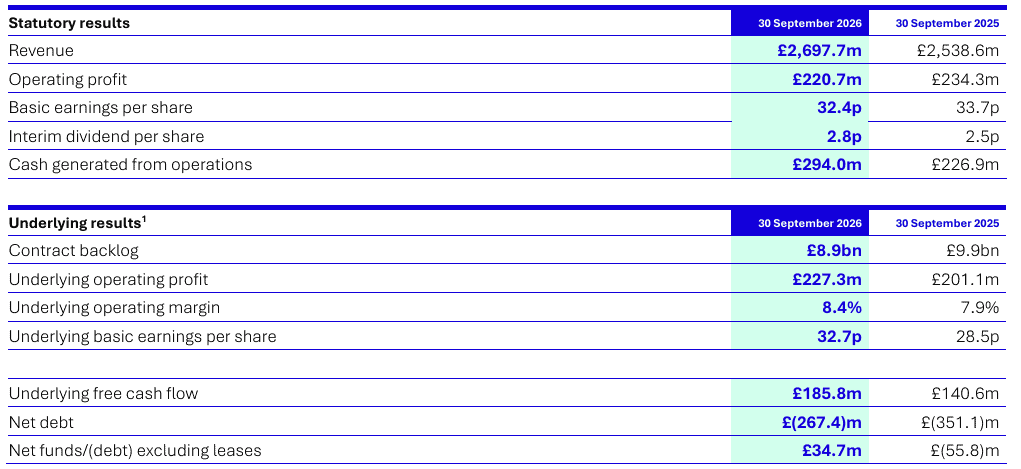
- Contract backlog: £8.9 billion, reflecting long-term contract execution, significant H2 order intake expected
- Revenue: £2,698 million, up 5% organically led by Nuclear and Aviation. Defence revenues grew 8%
- Underlying operating profit: £227 million, up 13%, with strong performance in Nuclear and Aviation
- Underlying operating margin: 8.4%, up 50 basis points, demonstrating good progress towards our medium-term target of at least 9%
- Underlying EPS: up 15% to 32.7p
- Underlying free cash flow: £186 million, with underlying operating cash conversion of 93%
- Net cash excluding leases of £35 million, a £91 million year-on-year improvement, reflecting strong cash generation
- Interim dividend 2.8 pence per share, up 12%
- Share buyback: around 40% of FY27 £200 million buyback complete at 18 November
- Outlook: FY27 expectations unchanged, with around 90% expected FY27 revenue under contract at 1 October 2026. Medium-term guidance reconfirmed
Consistently executing our strategy to drive good, long duration growth
- Expect to sign FMSP nuclear submarine and naval base support successor contract, ‘Gateway’, in November
- Established multiple collaboration agreements with UK and international companies to accelerate capabilities and position for emerging growth opportunities for example in the new hybrid nature of warfare
- Secured six-year Canadian submarine support extension, with a total value of CAD$1.2 billion
- Awarded Red Air contract for French Armed Forces, a new operational training activity for Babcock
- Secured key role in the UK SMR rollout with Great British Energy-Nuclear. Mobilisation under way
Supportive markets and evolving strategy expanding our growth opportunity
- Supportive market dynamics: Increasing defence spending in the UK and internationally, and growing demand for secure, low carbon nuclear energy, are expanding the opportunity across our established defence and nuclear capabilities
- CEO initial actions: Established new Growth, Transformation and Technology functions and reorganised internal structures to increase customer alignment, reduce complexity, improve execution and drive sustainable growth
- Strategy evolution: Continuing to grow and internationalise our core defence and nuclear businesses while leveraging our capabilities into two additional growth vectors – the new nature of warfare and national strategic resilience
Strong balance sheet, cash generation and disciplined capital allocation driving shareholder value
- Organic investment in infrastructure at Devonport and advanced manufacturing capabilities at our Rosyth facility
- New £200 million buyback launched in July. Expect to be complete by end of FY27 (around £80 million completed as at 18 November)
- 12% increase in the interim dividend to 2.8 pence per share
- Continue to assess pipeline of inorganic investment opportunities in line with our disciplined M&A strategy
Outlook
- For FY27, our expectations for another year of good progress are unchanged, supported by strong revenue visibility, with around 90% revenue under contract at 1 October 2026
- We reconfirm our medium-term guidance of average mid-single digit organic revenue growth, underlying operating margin of at least 9% and average underlying operating cash conversion of at least 80% across the period